Compare mortgage offers
See what each lender is charging for the same loan.
A closer look at your two offers.
Not total closing costs or cash to close. Other fees, prepaid items, escrow, and the cost of interest are not included.
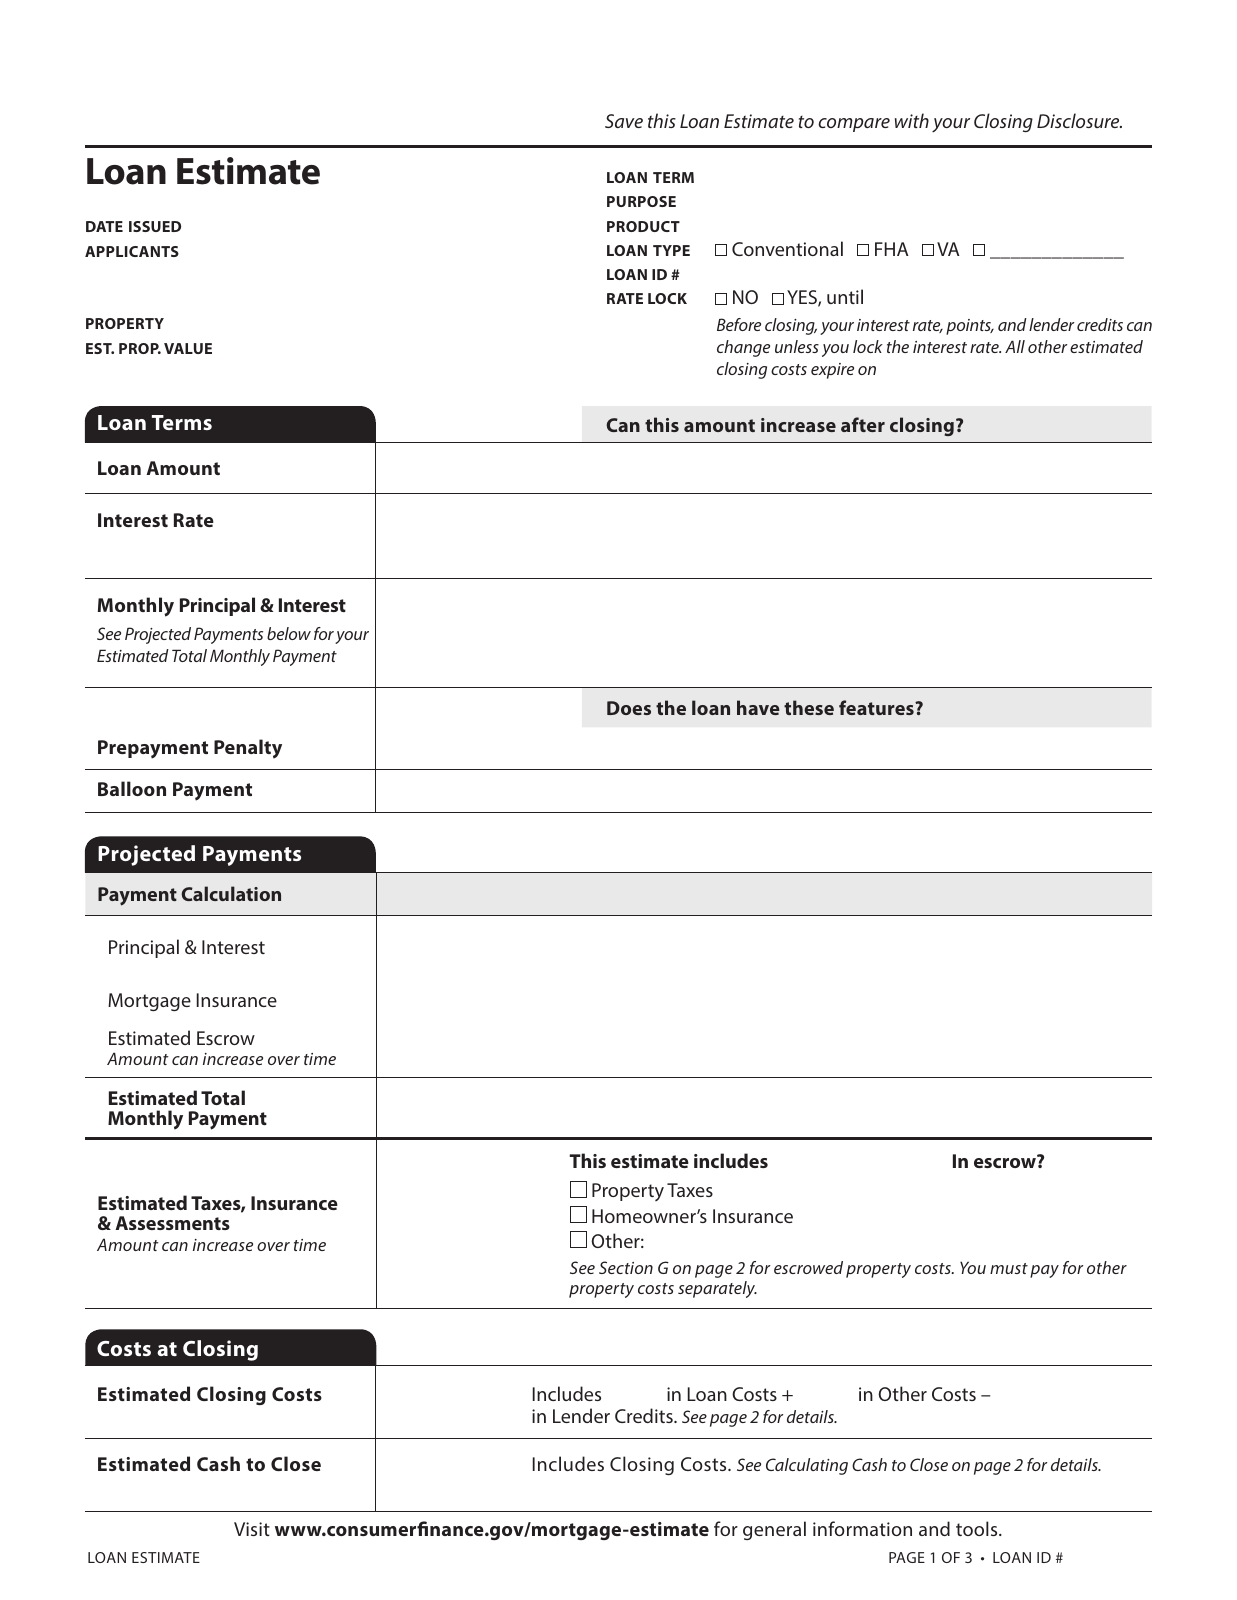
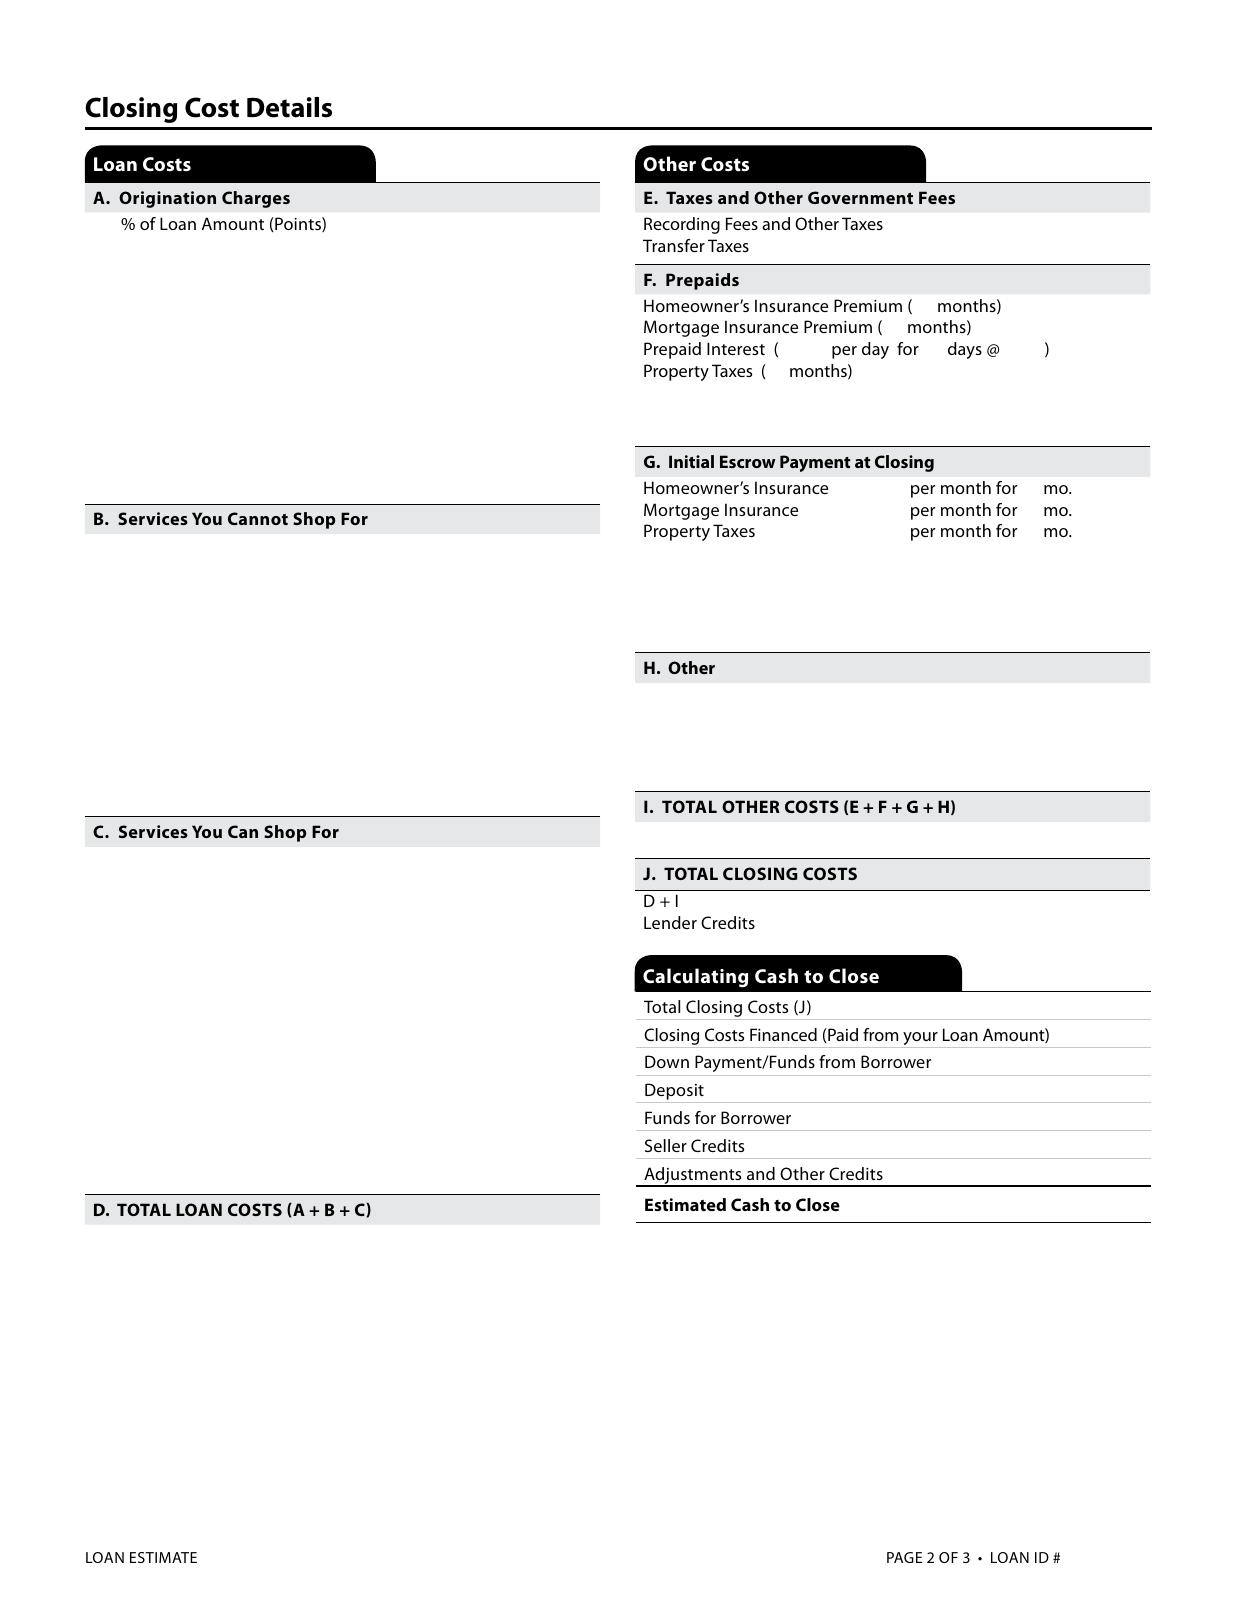
The rate and the charges belong together
A lower rate can come with higher upfront charges. Lender credits can reduce upfront costs while increasing the rate. Compare the tradeoff, not just the smaller number.
Kellibrooke does not charge a broker processing fee. Your official Loan Estimate and Closing Disclosure control the charges for your loan.
A few things to know
Where do I find these four figures?
Loan amount and interest rate are on page 1 of your Loan Estimate. Section A, Origination Charges, and lender credits in Section J are on page 2. Use the full Section A total, including any points.
What does Section A minus lender credits tell me?
It is a narrow comparison of origination charges after lender credits. It is not total closing costs, cash to close, or the cost of the loan over time. A negative result means credits exceed Section A, not cash paid to you.
Does a lower figure mean a better mortgage?
Not by itself. Compare the same loan type, term, property, and rate-lock period. Weigh the interest rate alongside the charges and credits, and review the complete Loan Estimates before choosing.
Sources: CFPB Loan Estimate explainer and comparing loan offers.
Educational comparison only, not a quote, approval, or loan offer. Review all loan terms and costs before deciding.
Want me to look at both offers?
I can explain the rate, charges, and credits without making this more complicated than it needs to be.